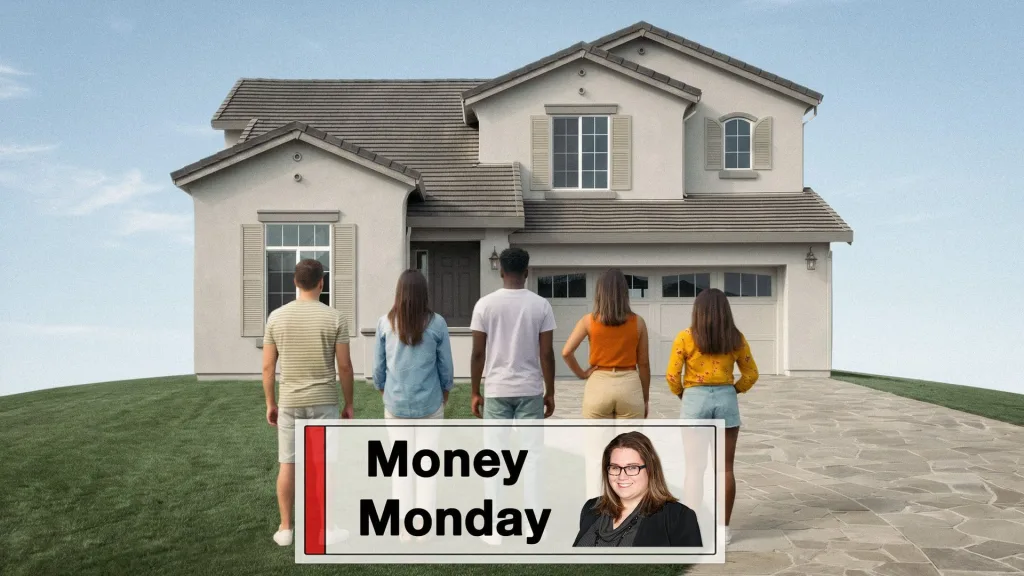
As mortgage rates reach their highest levels in a decade, many first-time homebuyers, particularly from Generation Z, are facing a daunting reality. This group, often characterized by their financial caution and aspirations for home ownership, is now grappling with the implications of these surging rates on their future.
Recent reports indicate that Gen Z buyers are holding out for mortgage rates below 5%. However, with the current economic climate and rising home prices, this expectation may be overly optimistic. The Toronto real estate market, for instance, has seen significant appreciation in home values, making affordable options increasingly scarce.
Current Trends in Home Prices and Mortgage Rates
The average mortgage rate has surged to nearly 7%, a stark contrast to the sub-3% rates that many buyers enjoyed just a couple of years ago. According to the Case-Shiller index, home prices have continued to rise despite economic uncertainties, further complicating the aspirations of young buyers.
As affordability declines, Gen Z must confront the reality that waiting for lower rates may not be a viable strategy. The longer they postpone home purchases, the more they risk being priced out of the market entirely. Experts warn that those who delay may find themselves in a worse position as home prices are projected to keep increasing, fueled by limited inventory and high demand.
The Impact of Rising Prices on Future Buyers
The challenge for Gen Z is not just about securing a mortgage at a favorable rate; it’s also about the overall affordability of homes. With median home prices climbing, the dream of home ownership is slipping further from reach. For instance, in markets like Vancouver, the median home price has skyrocketed, making it difficult for new buyers to enter the market.
As they navigate these financial waters, many Gen Z individuals are reconsidering their home-buying strategies. Some are looking into alternative financing options, such as adjustable-rate mortgages (ARMs), which may provide a temporary solution but come with their own risks. Others are exploring different locations or smaller properties as a means to get a foot in the door.
The reality is, while Gen Z may hold out hope for sub-5% mortgage rates, the evolving landscape of home prices and interest rates suggests that they will need to adapt their expectations and strategies if they wish to achieve their goal of home ownership.